-
Shop
- Adidas
- Advanced Technologies
- AI Skills Mastery 2026 Collection
- Best-Sellers
- Calvin Klein
- Car Accessories
- Confidence
- Dating & Social Skills
- Digital Resources
- AI & Technology
- AI Skills
- Beauty
- Budgeting & Saving
- Car Buying & Ownership
- Cozy Feast Collection
- Electronics & Technology
- Entrepreneurship & Business Growth
- Financial Education
- Financial Independence
- Financial Mindset & Psychology
- Goal Setting
- Hobbies
- Home Styling & Organization
- Kitchen & Recipes
- Leadership
- Mindset
- Online Business
- Parenting & Child Development
- Personal Style & Fashion
- Pet Lifestyle & Wellness
- Positive Thinking
- Sleep Improvement
- Stress Management & Relaxation
- Travel Planning
- Yoga & Fitness
- Yoga & Mind-Body Practices
- Education & Learning
- Family & Parenting
- Fashion
- Alexander McQueen
- Bags
- Bags & Wallets
- Balenciaga
- Belts
- Blazers
- Bottega Veneta
- Brunello Cucinelli
- Burberry
- Chanel
- Chloé
- Dior
- Dolce & Gabbana
- Dresses
- Etro
- Fendi
- Gucci
- Hats & Hair Accessories
- Hoodies & Sweatshirts
- Jacquemus
- Jewelry
- Jil Sander
- Keychains
- Kiton
- Luggage
- Miu Miu
- Off-White
- Prada
- Rick Owens
- Saint Laurent
- Socks & Tights
- Sweaters & Cardigans
- The Row
- Tom Ford
- Tops & Shirts
- Valentino
- Valentino Garavani
- Versace
- Vivienne Westwood
- Watches
- Furniture
- Gadgets
- Health & Beauty
- Health & Wellness
- Home & Garden
- Kids & Babies
- Kitchen
- Lighting
- Patio, Lawn & Garden
- Personal Growth
- Pet Care
- Pet Supplies
- Pets
- Shoes
- Smart Home Living Guides
- Sport & Outdoors
- Stress Relief & Relaxation
- TikTok Growth & Monetization Mastery
- Travel
- Travel & Adventure
- Wealth
- Wellness
- YouTube Shorts Best-Sellers
- Popular
- Best deals
Condo vs. House: A Clear Framework for Choosing
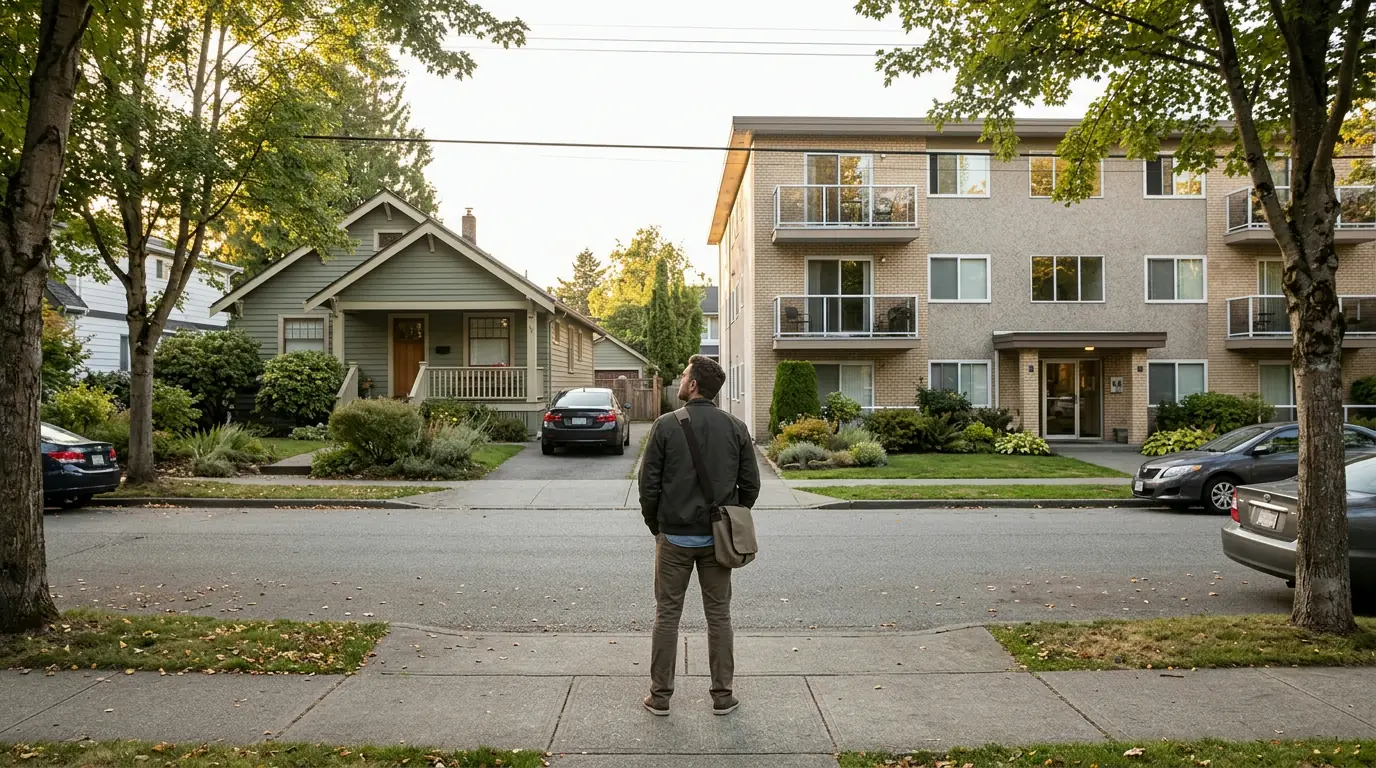
Condo or House: Choosing the Right Home for Your Life
The condo-versus-house decision is rarely about square footage alone. It’s about the rhythm of daily life: how much time you actually have for maintenance, how important privacy feels on a random Tuesday, what kind of community energizes you (or drains you), and how your finances behave under real-world stress tests. Our team put together a practical, no-drama way to compare both options—so your final choice fits what you need now and still makes sense a few years from today.
Start with the life you want to live (not the property you want to own)
Before you compare floor plans, build two “day-in-the-life” snapshots: one for weekdays and one for weekends. Include commute patterns, errands, pets, hobbies, hosting, and how much quiet time you protect. This is where condo vs. house differences show up quickly.
- Write down non-negotiables: elevator access, yard space, workshop/garage needs, transit proximity, walkability, school zones, and guest parking.
- Decide what gets delegated: lawn care, exterior repairs, snow removal, security, and shared amenities can shift from “your problem” to “the building’s system.”
- Name your friction points: noise sensitivity, shared walls, HOA rules, renovation limits, and storage caps are easier to handle when you acknowledge them up front.
- Set a realistic time budget for upkeep: a condo often trades surprise chores for a predictable monthly fee; a house often trades rules for hands-on responsibility.
Money realities: compare monthly cost and long-term exposure
A clean comparison uses an “all-in monthly number” for each option. That means adding every recurring cost line, plus a maintenance reserve—because the true cost of a home includes what you’ll eventually replace.
Monthly cost checklist to compare condo vs house
| Cost line item | Condo: include/estimate | House: include/estimate |
|---|---|---|
| Mortgage (P+I) | Yes | Yes |
| Property taxes | Yes | Yes |
| Homeowners insurance | HO-6 unit policy (plus HOA master coverage exists) | Full homeowners policy |
| HOA dues | Yes (major variable) | Usually no (unless HOA community) |
| Utilities | Often lower; confirm what HOA covers | Often higher; owner pays all unless included |
| Maintenance reserve | Lower for interior-only, but keep a buffer for assessments | Higher; plan for big-ticket replacements |
| Repairs responsibility | Mostly inside the unit; shared systems via HOA | Everything: structure, exterior, systems, yard |
| Parking/storage | May be deeded/assigned; sometimes extra fee | Typically included but varies by property |
When you look at condos, treat HOA dues as services + reserves, not just a fee. Confirm what’s included (water, trash, exterior maintenance, amenities) and what still lands on you. For houses, plan for irregular costs like roof work, HVAC replacement, exterior paint, landscaping, pest control, and bigger seasonal utility swings. If you want neutral homebuying guidance as you run numbers, resources from the Consumer Financial Protection Bureau (CFPB) and HUD can help you sanity-check the process.
Lifestyle trade-offs that show up after move-in
- Privacy and sound: shared walls and ceilings can be totally fine—or a daily stressor. Pay attention to building construction, house rules, and typical “noise hours.”
- Freedom to customize: houses usually allow more exterior and structural changes; condos often limit flooring, windows, balconies, and renovation timing.
- Community and convenience: condos can simplify life with common amenities and shared responsibilities; houses offer autonomy but require more personal oversight.
- Storage and gear: bikes, strollers, sports equipment, tools, and seasonal items need a plan—especially if storage rules are strict.
- Pets and guests: condos may have pet limits and guest policies; houses shift the focus to yard fencing, neighborhood norms, and your own boundaries.
Risk and stability: HOA health vs property upkeep
Risk looks different in a condo than it does in a house. With condos, you’re buying into a shared system—so the HOA’s financial health matters. With houses, you’re buying into a maintenance timeline—so the property’s condition and your repair buffer matter.
A decision framework that prevents “analysis paralysis”
Tools from our store to help you compare options clearly
- Condo or House Choosing the Right Home for Your Life | Smart Homebuying eBook on how to decide between condo vs house — Use it like a guided worksheet: priorities, cost categories, HOA/building questions, red flags, and a consistent scoring approach.
- Instant Wall-Mounted Electric Water Heater with LCD Display — If you choose a house, planning for system replacements is part of the ownership math; mapping “eventual upgrades” helps you size your maintenance reserve more realistically.
- Heart Shaped Crystal Ceiling Light — If you choose a condo with renovation limits, smaller interior upgrades (like lighting) can be a practical way to personalize your space without structural changes.
FAQ
How much should HOA reserves matter when choosing a condo?
HOA reserves matter because they’re the financial cushion for major shared repairs; weak reserves increase the odds of special assessments and surprise cash demands. Reviewing budgets, reserve studies (when available), and meeting minutes helps you see whether the building plans ahead or reacts late.
Is a house always better for building wealth than a condo?
No—appreciation depends heavily on location, market cycles, and the property itself, and “wealth” includes your all-in costs and time. Compare total monthly carrying costs, maintenance and assessment risk, and what you give up (or gain) in flexibility and opportunity cost.
What’s the simplest way to decide between condo vs house when both feel possible?
Use a weighted scoring sheet, then run a three-horizon check (6 months, 2–3 years, 5+ years) and a quick regret test for each option. A structured workbook keeps your comparisons consistent so you don’t get swayed by staging or a single emotional showing.
Recommended for you

Ostrich Feather Duster Lifespan: What to Expect
Oct 6, 2026



Leave a comment